Solana Tokenized Equities Hit 1.5 Million Holder Addresses — But the Real Story Is More Complicated
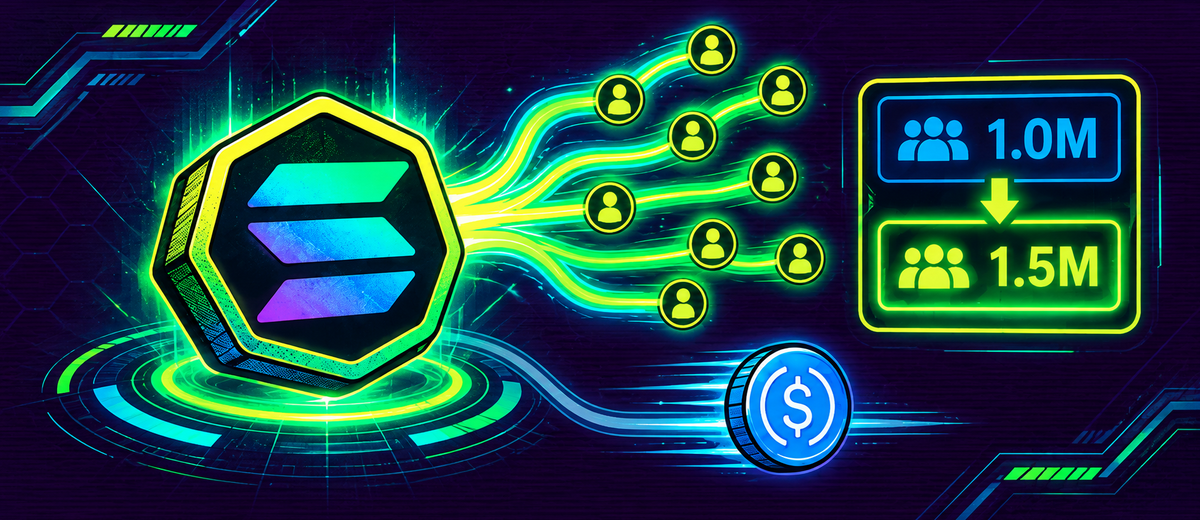
Solana's tokenized equity ecosystem reached a headline-grabbing milestone on October 26, 2026: 1.5 million holder addresses, a fivefold increase since August. The number has fuelled significant enthusiasm about blockchain-based stock trading gaining mainstream traction on one of crypto's fastest networks. Look closely at the data, however, and a more nuanced picture emerges — one shaped by address-based counting rather than unique investor counts, incentive programs that distributed $31 million in stock tokens to wallets that had never bought a tokenized stock before, and a trading volume figure in which nearly a third comes from memecoin pairs rather than conventional stock purchases. Understanding what the milestone actually measures is at least as important as the milestone itself.
Key Takeaways
Solana's tokenized equity holder count reached 1.5 million addresses on October 26, 2026 — a fivefold increase since August and a 50% jump from the 1 million wallets the Solana Foundation reported in September
The metric counts blockchain addresses, not unique investors — one person using multiple wallets can appear in the count more than once
Between August 3 and October 11, 2026, incentive programs distributed approximately $31 million in stock tokens across more than 360,000 wallets; nearly 80% of those recipients had no prior record of buying a tokenized stock
September trading volume for tokenized equities reached approximately $4.4 billion; outstanding tokenized equity value was $684 million
Between September 1 and October 11, memecoin–stock token trading pairs generated $1.76 billion in volume — 31.5% of the $5.58 billion total recorded in tokenized equity DEX activity during that span
Securitize enables qualifying investors to trade 12 tokenized U.S. stocks on Solana, including Apple, Nvidia, Tesla, and Microsoft; underlying shares back the products and transactions settle in USDC
Growth in tokenized equity activity does not translate proportionally into demand for SOL: most platforms allow settlement in USDC rather than the network's native token, with SOL required only for minimal transaction fees
The Headline: What a Fivefold Increase in Five Months Looks Like
The trajectory of Solana's tokenized equity holder count since August 2026 is genuinely striking, whatever caveats surround the metric's methodology.
In August, the holder count was at the baseline that implies the current figure is five times larger — somewhere in the range of 300,000 addresses. By September, the Solana Foundation was reporting 1 million wallets holding tokenized stock products, and September's trading volume reached approximately $4.4 billion across the tokenized equity market on the network. At that point, the total outstanding value of tokenized equities on Solana was approximately $684 million.
The month between September's 1 million figure and October 26's 1.5 million figure saw another 500,000 addresses added to the holder count — an acceleration that maintained the pace of growth despite the base already being larger. Combined, these figures represent one of the most rapid expansions in participation for any tokenized real world asset product on any public blockchain.
The question is what that expansion actually reflects in terms of genuine investor adoption — and it requires an honest look at the methodology behind the numbers.
The Measurement Problem: Addresses, Not Investors
The most important caveat in any analysis of Solana's tokenized equity holder count is one that the Solana Foundation's announcement does not foreground, but that Crypto.news — citing Blockworks — made explicit: the metric counts blockchain addresses containing tokenized equity products, not distinct investors.
This distinction is fundamental to how on-chain metrics work, and it is one that frequently misleads investors and media audiences who apply traditional financial market counting conventions to blockchain data.
In traditional finance, a "holder" of a stock is typically a unique account in a brokerage or custody system. While it is possible for one investor to hold the same security across multiple brokerage accounts, the friction involved means the count of accounts generally approximates the count of investors reasonably well.
On public blockchains, the relationship between wallets and investors is far less constrained. Creating a new blockchain wallet address costs nothing and takes seconds. A single investor can — and often does — operate dozens or hundreds of wallet addresses for different purposes: privacy, asset segregation, interaction with different decentralised applications, or simply out of habit. When on-chain metric providers count "holders" of a token, they count every unique address containing at least one unit of that token, regardless of how many addresses belong to the same underlying person.
The result is systematic overcounting of unique investors whenever wallet-based metrics are used. The scale of the overcounting is unknown without additional data — it could be modest (if most participants use a single primary wallet) or substantial (if sophisticated users are deliberately distributing holdings across many addresses). Without wallet clustering analysis or identity verification, there is no precise way to determine what share of the 1.5 million addresses represents genuinely distinct investors.
This is not a critique specific to Solana or to tokenized equities — it is a universal limitation of on-chain counting that affects holder metrics across every blockchain protocol and token. But it is particularly relevant when headline figures are used to argue for mainstream adoption of a new product category, as the 1.5 million number has been in this case.
Incentive Programs: Organic Growth or Reward Farming?
A second important factor shaping the holder count increase is the role of distribution incentives — rewards programs that paid users in stock tokens for participating in the tokenized equity ecosystem.
Between August 3 and October 11, 2026, incentive programs distributed approximately $31 million worth of stock tokens across more than 360,000 wallets. That figure — 360,000 wallets receiving rewards — accounts for a meaningful portion of the total holder count increase over the same period, since each recipient wallet would be counted as a tokenized equity holder upon receiving the tokens.
The most telling detail is not the number of reward recipients but what those recipients had done before receiving the incentive: nearly four out of five of them had no prior record of buying a tokenized stock. Put differently, approximately 80% of the wallets that received incentive distributions in the August–October window were new to tokenized equity ownership — they arrived in the ecosystem through the reward program, not through an independent decision to invest in tokenized stocks.
This pattern is well-documented in blockchain ecosystems under the general heading of "incentive farming" or "airdrop farming" — a behaviour in which participants engage with a protocol's products primarily or exclusively to capture the incentive, with no intention of remaining active participants once the reward program ends. Farming behaviour inflates participation metrics during the incentive period and frequently produces a sharp drop in activity once distributions cease, as the purely incentive-driven participants exit.
This does not mean every wallet that received incentive tokens was a short-term farmer — some portion of those 360,000 wallets may have become genuinely engaged investors in tokenized equities. But the data does not allow that portion to be cleanly separated from the farming-driven participants, which means the incentive contribution to the headline holder count is an important analytical asterisk that the top-line figure does not communicate.
What Is Actually Available: Securitize's 12 Tokenized U.S. Stocks
Setting aside the measurement caveats, the infrastructure underpinning Solana's tokenized equity market has genuine substance.
Securitize — a leading digital securities platform that has been involved in tokenizing real-world financial assets for institutional and retail markets — enables qualifying investors to trade 12 tokenized U.S. stocks directly on the Solana blockchain. The available tokens include shares of some of the world's most recognisable and widely traded companies: Apple, Nvidia, Tesla, and Microsoft are among the names explicitly confirmed, with eight additional companies completing the list of 12.
The product design reflects what institutional market participants consider the necessary foundation for tokenized equity credibility: the underlying actual shares back each token on a one-to-one basis, meaning the tokens represent claims on real securities held in custody rather than synthetic or derivative instruments. Transactions settle in USDC — Circle's dollar stablecoin — making the products accessible to participants who hold dollar-denominated digital assets without requiring them to acquire SOL.
Securitize's participation adds institutional credibility to the ecosystem. The firm has established relationships with regulated custodians and has experience navigating securities law compliance in the U.S. context — both prerequisites for a tokenized stock product that purports to offer genuine ownership exposure to publicly traded equities.
The qualification requirement for participation also reflects the regulatory reality of tokenized securities in the current U.S. environment. Not every Solana wallet holder can access these products — investors must complete an onboarding process that includes identity verification and, depending on the specific product structure, may require investor accreditation or other qualification steps. This regulatory gating is one reason why raw address counts are a poor proxy for the investable market that Securitize and similar platforms actually serve.
Trading Volume: When Memecoins Meet Stock Tokens
The September trading volume figure of approximately $4.4 billion sounds like evidence of a thriving, liquid tokenized equity market. The composition of that volume, however, tells a more complicated story.
Between September 1 and October 11, 2026, trading pairs that combined memecoins with tokenized stocks generated $1.76 billion in cumulative volume on decentralised exchanges — accounting for 31.5% of the $5.58 billion total in tokenized equity DEX activity recorded over that period.
To understand what this means, it helps to understand what a memecoin–stock token trading pair is and why it exists on a decentralised exchange.
Solana has been home to one of the most active memecoin ecosystems in crypto, driven in large part by platforms like Pump.fun and its successors, which allow users to create and trade speculative tokens with minimal friction. When platforms such as StonkFun and Pump introduced trading pairs that allowed memecoins to trade directly against stock tokens — placing, say, a speculative Solana memecoin on one side of a trade and an Apple or Nvidia stock token on the other — these pairs were classified as "tokenized equity trading activity" in the volume statistics, since one leg of each trade involves a stock token.
The economic motivation for memecoin–stock token pairs is not straightforward investment in tokenized equities. It is more typically speculative trading activity: using stock tokens as a relatively stable, liquid counter-asset in pairs against volatile memecoins, or using the pair structure to access liquidity for memecoin trading. The stock token's presence in the pair does not imply that the trader has any investment thesis about the underlying company.
The practical consequence is that roughly $1 out of every $3 recorded as "tokenized equity DEX volume" during the measured period reflects this memecoin trading behaviour rather than direct investment in tokenized stocks. Stripped of that activity, the volume figure drops from $5.58 billion to approximately $3.82 billion — still a meaningful number, but materially different from the headline.
The SOL Demand Question: Does Tokenized Equity Growth Benefit SOL Holders?
For investors in SOL — Solana's native network token — one natural question is whether the explosion in tokenized equity activity translates into meaningful demand for SOL itself. The answer is more complicated than simple growth narratives might suggest.
Solana requires SOL for network transaction fees — every on-chain transaction, regardless of what assets it involves, requires a small amount of SOL to compensate the validators that process and confirm it. Solana's transaction fees are genuinely minimal — typically fractions of a cent — by design, as low fees are a core part of the network's value proposition for high-throughput applications. This means that a very large number of tokenized equity transactions generates a very small aggregate SOL fee demand relative to the total transaction value.
More significantly, the dominant settlement mechanism for tokenized equity products on Solana is USDC rather than SOL. Securitize's products accept USDC for settlement, and many platforms allow investors to buy stock tokens with stablecoins directly. An investor who acquires tokenized Apple stock using USDC on a Solana DEX consumes a tiny fraction of a SOL in transaction fees, but does not need to buy SOL in any meaningful quantity to complete the transaction.
This is a structural feature of the stablecoin-settled tokenized asset model that distinguishes it from the native token utility models that drive demand for chains where gas fees are paid in more expensive native tokens. While tokenized equity growth on Solana is genuinely bullish for the network's throughput utilisation and its positioning as an infrastructure layer for financial applications, its direct impact on SOL price through fee demand is limited by the decimal-place-small size of each fee payment.
The indirect effects may be more significant over time: a network demonstrating genuine non-speculative utility at scale, attracting regulated financial institutions and their user bases, building a track record of processing trillions in annualised financial transaction value — these outcomes could support SOL's valuation through the credibility and adoption narrative rather than directly through fee mechanics.
Putting the Milestone in Its Proper Context
The honest assessment of Solana's 1.5 million tokenized equity holder figure is that it reflects genuine progress in a genuinely important product category, alongside several inflation factors that make the raw number an imprecise indicator of actual investor adoption.
What the number reflects accurately:
The Solana network has established meaningful infrastructure for tokenized equity products, with credible institutional participants like Securitize offering regulated, backed tokens
Trading volumes, while partially inflated by memecoin pairs, represent real on-chain economic activity at a scale that few blockchain networks have achieved for non-speculative asset categories
Participation has grown rapidly, and some portion of that growth represents genuinely new engagement with tokenized financial products by users who would not previously have had low-friction access to U.S. equities
What the number does not reflect accurately:
The count of unique investors, since wallet addresses overcount individual participants by an unknown but potentially significant factor
Organic investor demand independent of incentive programs, since approximately 80% of incentive recipients were new to tokenized stocks and may not persist as active investors
Conventional investment intent across all trading volume, since nearly a third of DEX volume comes from memecoin trading pairs rather than direct stock purchases
Proportional benefits to SOL token holders, since stablecoin settlement means tokenized equity growth generates minimal fee demand for the native token
Why Tokenized Equities on Blockchain Matter Despite the Caveats
None of the measurement nuances above diminish the genuine significance of what is being built in Solana's tokenized equity ecosystem — and it is important to hold both the critical analysis and the broader strategic picture in view simultaneously.
Tokenized equities represent one of the most compelling applications of blockchain technology for mainstream financial markets. For global investors without easy access to U.S. stock markets — whether due to geographic, regulatory, or financial barriers — blockchain-based access to Apple, Nvidia, Tesla, and Microsoft shares through a stablecoin-settled DEX represents a meaningful expansion of financial access that was not possible through traditional channels.
The settlement efficiency argument is also real: blockchain-native settlement can occur in seconds rather than the T+2 (trade date plus two business days) standard that governs conventional U.S. equity markets, reducing counterparty risk and unlocking capital faster. For traders and institutions operating across time zones and market hours, continuous settlement availability adds genuine value.
The 24/7 trading capability is similarly significant. U.S. stock markets operate during specific hours on business days; tokenized equity markets on public blockchains operate continuously. For investors in Asia, Europe, or other time zones where U.S. market hours are inconvenient, this represents a structural improvement in access.
These utility arguments will likely drive genuine organic adoption of tokenized equities over time — adoption that will be more durable than incentive-driven wallet creation and less noise-contaminated than memecoin DEX volumes. Solana's 1.5 million addresses may overcount today's genuine investors by a significant margin. The question for the longer term is whether the infrastructure, regulatory framework, and product quality are sufficient to convert that overstated current figure into a justified future one.
Summary
Solana's tokenized equity ecosystem reached 1.5 million holder addresses on October 26, 2026 — a fivefold increase since August that reflects both genuine infrastructure development and several factors that inflate the raw participation numbers. The metric counts wallet addresses rather than unique investors, allowing individual participants to appear multiple times. Approximately $31 million in incentive distributions reached more than 360,000 wallets between August and October, and nearly 80% of those recipients were first-time tokenized stock holders — suggesting a significant incentive-farming component to the growth. Of the $5.58 billion in tokenized equity DEX volume recorded between September 1 and October 11, $1.76 billion (31.5%) came from memecoin-stock token trading pairs rather than direct equity investment. Securitize's 12 tokenized U.S. stocks — including Apple, Nvidia, Tesla, and Microsoft — settle in USDC and are backed by real underlying shares, providing genuine institutional infrastructure beneath the headline figures. SOL itself benefits modestly from this activity through minimal transaction fees rather than proportional demand, since stablecoin settlement is the dominant model. The milestone signals meaningful progress in one of blockchain's most important mainstream finance applications, but the most honest reading of the data sits somewhere between the headline achievement and the measurement noise that surrounds it.
Want to join the discussion? Login and create a profile to comment.